Filing an insurance claim after an injury should be straightforward: you report what happened, provide documentation, and receive fair compensation for your losses. Unfortunately, insurance companies don’t always see it that way. When an insurer disputes your injury claim, denies it outright, or offers a settlement far below what you believe you deserve, it can feel overwhelming. Knowing how to respond calmly and strategically can make all the difference in the outcome.
Understand Why the Claim Was Disputed
Before taking any action, read the denial or dispute letter carefully. Insurance companies are typically required to explain their reasoning, whether it’s a question of liability, the extent of your injuries, missing documentation, or a dispute over policy coverage. Understanding the specific reason behind the denial helps you determine your next steps and whether the insurer’s position has merit or appears to be an attempt to minimize payout.
Common reasons for disputes include:
- Disagreement over who was at fault for the incident
- Claims that injuries were pre-existing or unrelated to the event
- Insufficient medical evidence or documentation
- Allegations that the claim was filed too late
- Policy exclusions the insurer believes apply to your situation
Gather and Organize Supporting Documentation
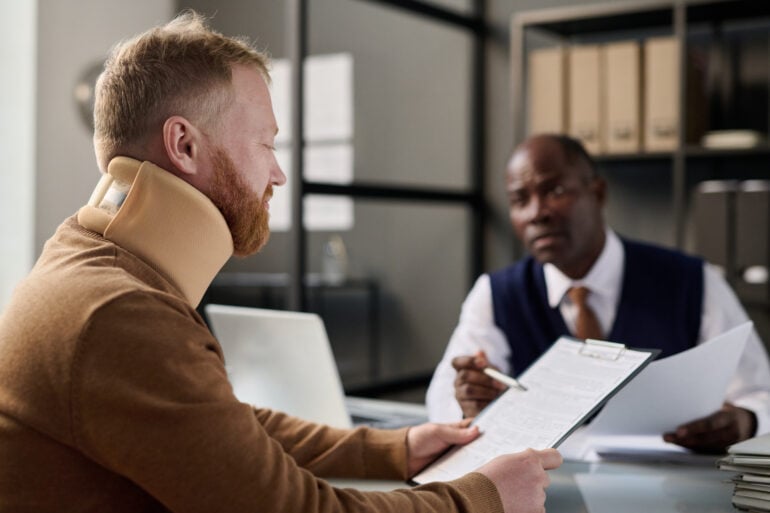
Once you know why your claim was disputed, start building a case to counter it. This means collecting every piece of evidence related to your injury and the incident itself. Medical records, bills, photographs of the scene, witness statements, and correspondence with the insurance company can all strengthen your position.
If your dispute centers on the severity of your injury, consider requesting a detailed written opinion from your treating physician that clearly connects your injury to the incident in question. Thorough documentation makes it much harder for an insurer to argue that your claim lacks merit.
Respond Promptly and in Writing
Timing matters when disputing an insurance company’s decision. Most policies and state regulations include deadlines for appealing a denial, so don’t let the clock run out while you consider your options. Respond in writing, keep copies of everything you send, and avoid giving recorded statements without fully understanding how they might be used.
Be factual and specific in your response. Reference the policy language, cite the documentation you’ve gathered, and clearly explain why you believe the insurer’s decision was incorrect. Emotional appeals rarely sway claims adjusters, but clear, well-supported arguments often do.
Know When to Seek Legal Advice
If the insurance company continues to dispute your claim despite your best efforts, it may be time to seek legal advice. A lawyer who focuses on injury claims can review your case, identify weaknesses in the insurer’s position, and advise you on whether an appeal, negotiation, or lawsuit is the best path forward.
Legal counsel from an experienced law firm can also handle communications with the insurance company on your behalf, which often changes the tone of negotiations. Insurers are frequently more willing to negotiate fairly once they know a knowledgeable attorney is involved, since it signals that you’re prepared to pursue the claim through formal channels if necessary.
Don’t Accept a Lowball Settlement Out of Frustration
It can be tempting to accept whatever amount the insurer offers just to put the dispute behind you, especially if you’re dealing with medical bills and lost income. But settling too quickly, or for too little, can leave you covering costs that should have been the insurer’s responsibility. Before accepting any settlement, make sure it accounts for your current and future medical needs, lost wages, and any long-term impact of your injury.
Final Thoughts
Disputes with insurance companies are stressful, but they don’t have to end in an unfair outcome. By understanding the reason for the dispute, gathering strong documentation, responding promptly, and knowing when to bring in legal counsel, you put yourself in the best position to receive the compensation you deserve. A disputed claim isn’t necessarily a lost cause, it’s simply the next step in making sure your case is heard fairly.